
What is an Emirates ID? The UAE identity card explained
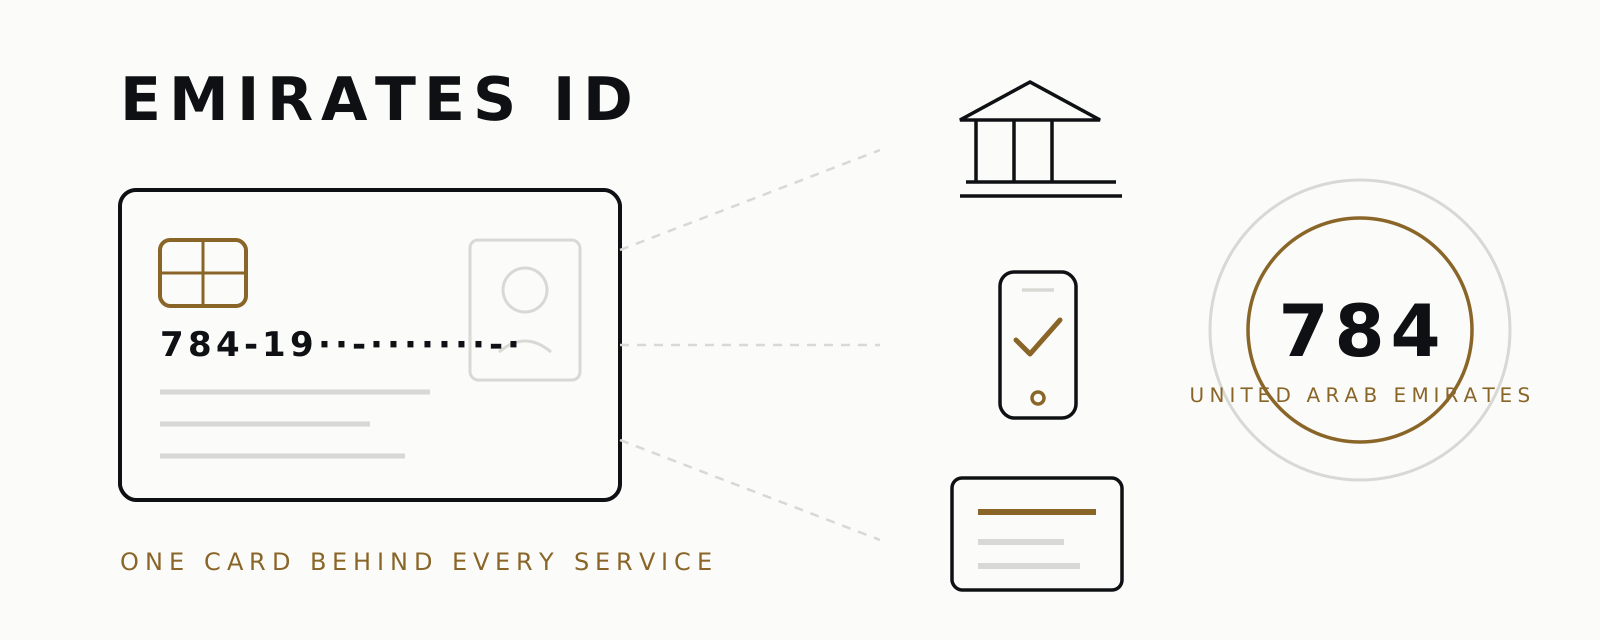
The Emirates ID is the UAE's mandatory identity card for citizens and residence-visa holders, issued by the Federal Authority for Identity, Citizenship, Customs and Port Security (ICP). It carries a 15-digit number, a biometric chip, and anchors your bank account, your KYC checks and your settlement details.
KEY FACTS
| What it is | Mandatory identity card for UAE citizens and residents |
|---|---|
| Issued by | ICP — Federal Authority for Identity, Citizenship, Customs and Port Security |
| Number format | 15 digits, starting 784 and embedding the birth year |
| Validity (residents) | Matches the residence visa (1, 2, 3, 5 or 10 years by visa type) |
| Used for | Bank accounts, KYC, telecom, tenancy, government services |
Source: ICP and the UAE Government portal, as of September 2026.
How does the Emirates ID work in the UAE?
The Emirates ID works as the single identity record behind almost every service in the UAE: banking, telecom contracts, tenancy registration, health insurance and government portals all key off the same card. Every resident meets it in the first weeks after arrival — it is also the document a licensed desk asks for when you sell USDT in Dubai as a UAE resident.
The card's 15-digit number starts with 784, the UAE's international country code, followed by the holder's birth year, a serial and a check digit. The chip stores the photograph, signature and fingerprint biometrics, and the same record powers UAE PASS, the national digital-identity login, and doubles as a payment address on Aani, the instant payment rail.
For citizens the card is valid for years at a time; for residents its validity matches the residence visa, so a visa renewal means a card renewal. Renewal runs through the ICP, in person or through its smart services, as of September 2026.
What role does the Emirates ID play in KYC and banking?
The Emirates ID is the primary identity document for anyone holding a UAE residence visa: banks open the account against it, and every licensed financial institution verifies it during KYC — the Know Your Customer check required by UAE anti-money laundering law. Non-residents are identified on a passport instead.
At a crypto desk the logic is identical. A resident selling USDT provides a passport plus the Emirates ID, because the payout account itself is registered to that card. The desk's check and the bank's check read from the same identity record, which is why the details must match exactly — name spelling, ID number, account holder. Identity is the first layer; at size the desk also asks for proof of where the funds came from.
Companies follow the same pattern one level up: the trade licence identifies the entity, and each signatory and beneficial owner is identified personally. The full document list sits in our onboarding section.
Why does the Emirates ID matter when you sell USDT?
The Emirates ID matters when you sell USDT because the settlement lands in a bank account tied to that card. A licensed desk pays only to an IBAN in your own name, and if the identity record behind that account has expired, the bank can restrict the account — with your wire arriving into it.
UAE banks review accounts whose Emirates ID on file has passed its expiry date and can limit transactions until the renewed card is registered. This is one of the commonest avoidable causes of a frozen settlement; the mechanics and the fixes are covered in our guide on how to avoid a bank freeze on crypto proceeds.
The card also works in your favour. A wire from a VARA-licensed desk to your own Emirates ID-registered account is an ordinary, explainable bank credit — the licence number behind the desk is checkable in the public register, linked from our licence section.
A worked example: one expired card, one delayed settlement
A UAE resident agrees to sell 400,000 USDT at a 0.15% spread. At the 3.6725 peg the gross value is AED 1,469,000; the spread costs AED 2,203.50, leaving AED 1,466,796.50 net. Figures are indicative, as of September 2026 — the spread band of 0.08% to 0.40% depends on ticket size.
The desk clears the trade and wires the same day by UAEFTS. The client's Emirates ID, however, expired the previous month, and the bank holds the inbound transfer pending the renewed card. The money is not lost, but the client spends days on renewal and a branch visit instead of having funds the same business day.
The lesson costs nothing: check the card's expiry date before you schedule the trade, not after. Renewals are routine through the ICP, but they do not run at the speed of a same-day settlement.
FAQ
Can I sell USDT in the UAE without an Emirates ID?
Yes, if you are not a UAE resident — a licensed desk onboards non-residents on a passport and proof of address. Residents should expect the Emirates ID to be requested alongside, because their bank account is tied to it.
Does an expired Emirates ID affect my bank account?
Yes. UAE banks can restrict or freeze an account once the Emirates ID on file expires, until you register the renewed card. Check the expiry date before scheduling a large settlement.
Is the Emirates ID the same as UAE PASS?
No. The Emirates ID is the physical card with a chip; UAE PASS is the national digital identity app built on the same record. Banks and government services accept UAE PASS as a login, but the card remains the underlying document.
Do tourists need an Emirates ID?
No. The card is mandatory only for UAE citizens and residence-visa holders. Visitors trade and bank on their passport, with a home-country proof of address for onboarding.
KYC once, then same-day settlement on every trade
Meridian OTC is a VARA-licensed Broker-Dealer in Dubai. Account approval takes one business day in most cases; after that, AED settles the same business day you trade, to an account in your own name. All-in spread 0.08–0.40% by size, published openly.
SOURCES
- Federal Authority for Identity, Citizenship, Customs and Port Security (ICP) — issuing authority for the Emirates ID, accessed 11 September 2026.
- UAE Government portal — Emirates ID — card purpose, number and services, accessed 11 September 2026.
- UAE Government portal — general provisions for the residence visa (Emirates ID expires with the visa; visa terms of 1, 2, 3, 5 or 10 years), accessed 14 September 2026.
- Meridian OTC onboarding requirements and published pricing bands — Meridian OTC published pricing bands, September 2026.
This guide is informational and is not legal, tax or investment advice, nor an invitation to buy or sell any virtual asset. Rules and figures are as of September 2026 — re-check the sources before acting. Virtual assets may lose their value in full or in part and are subject to extreme volatility.