
What are nostro and vostro accounts?
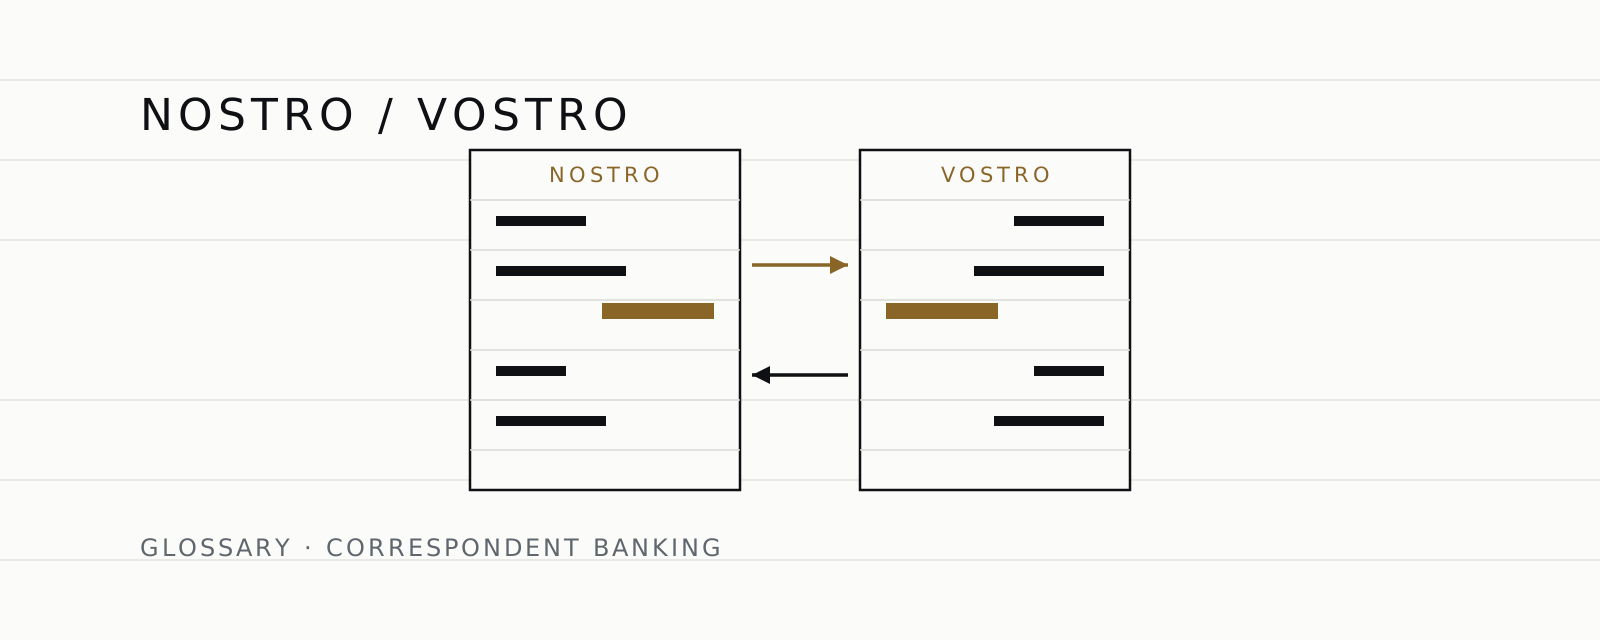
A nostro account is an account a bank holds with a foreign bank in that bank's currency — "ours" from the holder's side. The same ledger is the vostro — "yours" — for the bank that holds it. These paired accounts are what actually move a SWIFT payment.
KEY FACTS
| What it is | Two names for one correspondent account between banks |
|---|---|
| Nostro | "Ours" — the account your bank holds with a foreign bank |
| Vostro | "Yours" — the same account on the other bank's books |
| USD from the UAE | Settles on a US correspondent's ledger; 2–5 business days |
| AED inside the UAE | UAEFTS, same business day |
| Meridian USD payout | 2–5 business days, own-name accounts only |
Source: BIS Committee on Payments and Market Infrastructures (correspondent banking mechanics) and Meridian OTC settlement terms, as of September 2026.
Nostro and vostro: one account, two names
Nostro and vostro are the same bank account seen from two sides. Nostro is Latin for "ours": the account Bank A holds with Bank B, in Bank B's currency, recorded on Bank A's books. Vostro is Latin for "yours": that identical account as Bank B records it.
Every entry appears on both ledgers as a mirror image — a credit on the nostro is a debit on the vostro. Reconciling those two views every day is a core back-office job in correspondent banking.
These paired ledgers are the ground layer under the SWIFT messaging network. SWIFT carries the instruction; the nostro–vostro pair is where the value actually changes hands.
| Term | Latin | Whose view | On the books it reads |
|---|---|---|---|
| Nostro | "Ours" | Bank A's view of its account at Bank B | "Our dollars at Bank B" |
| Vostro | "Yours" | Bank B's view of the same account | "Bank A's dollars with us" |
| Loro | "Theirs" | A third bank's view of Bank A's account | "Their account at Bank B" |
One account, three descriptions — nostro and vostro are the two that matter for any cross-border payment.
How nostro accounts work for a UAE bank
A UAE bank cannot hold US dollars inside the UAE — dollar settlement happens in the United States. So the bank keeps a USD nostro account with an American correspondent, typically in New York, and pre-funds it so client payouts can be made without waiting.
When a Dubai client receives a dollar payout, no money crosses a border in real time. The sender's bank sends an MT103, the credit posts to the UAE bank's nostro at the correspondent, and only then does the UAE bank credit the client's account.
Dirhams skip all of this: AED moves domestically over the same-day UAEFTS rail operated by the Central Bank of the UAE. The nostro layer appears only when the payment crosses into a foreign currency.
Correspondent relationships are expensive to maintain, and BIS CPMI data has tracked a decade-long decline in their number worldwide — about 20% fewer active relationships between 2011 and 2018, with the decline continuing since. Fewer correspondents means longer chains — one reason routing for exotic currency pairs keeps getting slower.
Why this is what makes SWIFT take 2–5 days
The 2–5 business day range for USD wires from the UAE is mostly nostro mechanics, not messaging speed. The SWIFT message travels in seconds; the ledger entries across one to three correspondent pairs are what take days.
Each correspondent works its own business days and applies its own cut-off. A wire approved in Dubai on Thursday afternoon misses the New York cut-off, waits out the weekend, and starts moving on Monday at the earliest.
Compliance adds the rest. Every bank on the chain screens the payment against its source-of-funds picture, and a query pauses the entry on that bank's vostro ledger until the answer arrives.
The cost side of the same chain — OUR/SHA/BEN fees and correspondent deductions — is mapped in our piece on SWIFT transfers sent from the UAE.
Why it matters when you sell USDT
When you sell USDT in Dubai through a licensed desk and elect dollars, the payout reaches your bank through exactly this machinery. The desk's bank sends the wire, and one to three nostro–vostro pairs stand between it and your account.
Choose AED and the trade settles on-chain in minutes and lands the same business day. Choose USD and the on-chain leg is just as fast — it is the correspondent leg that takes 2 to 5 business days, as of September 2026 — the full dollar route is in our guide to selling USDT for US dollars.
These ledgers are also why licensed desks pay out only to accounts in your own name. Your bank can match the incoming wire to your documented profile — often years of WPS salary credits — without freezing the funds, because the sender and purpose are visible on its vostro-side records.
Worked example: a USD 400,000 payout from a USDT sale
You sell 400,000 USDT at an all-in spread of 0.15% — inside Meridian's published spread bands of 0.08%–0.40% by ticket size, as of September 2026. The spread costs USD 600, so the desk's bank wires USD 399,400 to your own-name account.
The wire leaves Dubai on Tuesday at 11:00 GST, after the New York cut-off. On Wednesday the first correspondent posts the entry on its vostro ledger and passes the payment on; on Thursday your bank's nostro at the next correspondent is credited, and your bank credits you. Value date: Thursday, two business days after the trade.
Had the same trade paid out in AED, the dirhams would have arrived on Tuesday itself. The currency you choose, not the desk, sets the settlement clock.
FAQ
Is a nostro account the same as a vostro account?
Yes — they are two names for one account. The bank that keeps money abroad calls it nostro ("ours"); the bank holding the money calls the same account vostro ("yours"). Every transaction posts to both ledgers as a mirror entry.
What is a loro account?
Loro is Latin for "theirs". When Bank A talks to Bank C about the account Bank A holds with Bank B, it calls that account a loro. You rarely meet the term outside correspondent-banking departments.
Can an individual or a company open a nostro account?
No. Nostro accounts exist only between regulated financial institutions. Clients meet them indirectly — through correspondent deductions and the 2–5 business day timeline on foreign-currency wires.
Do nostro accounts have anything to do with crypto?
Only at the settlement step. A USDT sale settles on-chain in minutes, but the fiat payout still travels across correspondent ledgers. Dollars mean a nostro chain and 2–5 business days; dirhams mean UAEFTS the same business day.
Sell USDT with a settlement date you can plan around
Meridian OTC is a VARA-licensed Broker-Dealer in Dubai (licence VL/24/03/017). USD settles by SWIFT in 2–5 business days to own-name accounts; AED settles by UAEFTS the same business day. Spread 0.08–0.40% by ticket size, published openly.
SOURCES
- BIS Committee on Payments and Market Infrastructures — correspondent banking, accessed 11 September 2026.
- SWIFT — about the cooperative, accessed 11 September 2026.
- Central Bank of the UAE — payment systems (UAEFTS), accessed 11 September 2026.
- Meridian OTC published pricing bands and settlement terms, September 2026.
- The Clearing House — CHIPS, the New York-based USD clearing system, accessed 14 September 2026.
- BIS — CPMI data on correspondent banking networks: 20% reduction in relationships over seven years (May 2019), accessed 14 September 2026.
This guide is informational and is not legal, tax or investment advice, nor an invitation to buy or sell any virtual asset. Rules and figures are as of September 2026 — re-check the sources before acting. Virtual assets may lose their value in full or in part and are subject to extreme volatility.